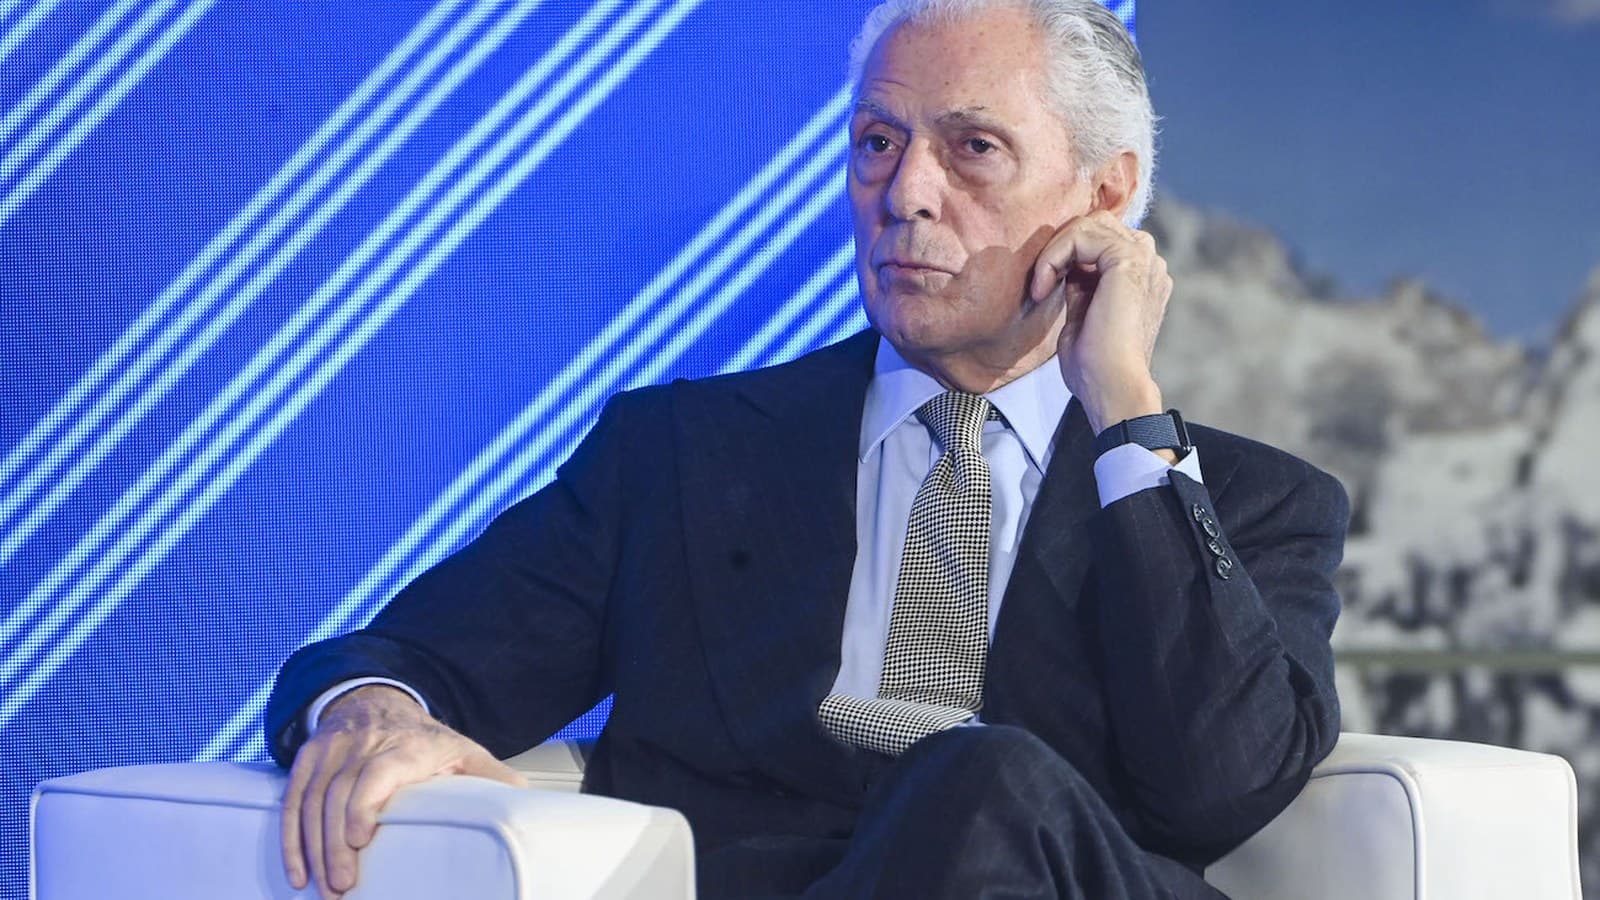
Marco Tronchetti Provera has brought his stake in Pirelli to 29,9 percent, a number that looks almost too precise to be an accident, because it is not one. Under Italian securities law, crossing 30 percent of a listed company triggers a mandatory takeover bid for the rest of the shares, an obligation expensive and complicated enough that Tronchetti Provera's holding structure, Camfin Alternative Assets, Camfin and Longmarch Holding, has spent two years buying just enough Pirelli stock to consolidate control without tripping that wire.
The latest move was a 3,34 percent block bought from a bank, following a path that started in January 2024, when Camfin held 14 percent, and picked up pace in October 2024, when Tronchetti Provera was authorized to buy up to 29,9 percent within 24 months. The stake climbed to 25,28 percent after Brembo exited its 5,58 percent position, and reached the authorized ceiling this September, right on schedule and right at the edge of the threshold that would have forced a far larger and far more expensive transaction.
None of this came free. The buying was backed by a 650 million euro refinancing arranged by UniCredit and Intesa Sanpaolo, along with a 158,75 million euro capital increase for Camfin Alternative Assets carried out in two tranches. Longmarch Holding, the vehicle that unites the Tronchetti Provera family with its longtime Chinese partner Niu, sits underneath the structure, keeping the arrangement's Italian Chinese balance intact even as the Italian side of it grows.
The timing lines up with a broader reshuffling of Pirelli's ownership. Weeks earlier, Sinochem sold 14 percent of the company to Lumina Crown, the investment vehicle of the Czech defense fortune built by Michal Strnad, in a block worth about 987 million euros, a deal that dropped the Chinese group's stake to roughly 20,1 percent. Between that sale and Tronchetti Provera's own purchases, Camfin has reclaimed its position as Pirelli's largest shareholder, restoring the balance of power that existed before Sinochem's larger holding briefly outweighed it.
What Tronchetti Provera has bought, in effect, is de facto control of Pirelli's governance without paying for de jure control of the entire company. Ninety nine hundredths of a percentage point below 30 is not an accident of timing, it is the precise cost benefit calculation of a shareholder who wants the company run his way without having to buy out everyone who disagrees with him.